Managing money as a couple sounds simple until you actually try it.
There are shared bills, individual purchases, subscriptions, savings goals, and expenses that one person paid for but both people use.
Then comes the awkward question: How much should we actually share?
A joint bank account solves one part of the problem. But it also means combining money more completely than some couples want.
That is exactly where Honeydue takes a different approach.
This finance app (for couples) was created around a simple idea: helping couples manage money together without sharing every financial detail with one another.
Personally, I loved the idea around which the app was built. Also, the app helps partners connect their accounts and monitor expenses, coordinate bills, and even help split expenditures.
Plus, you can control how much financial information your partner can see on the app. That’s where Honeydue stops being just another budgeting app.
Instead, it is more of an interesting tool that not just manages your money but also your boundaries – for couples, it’s a complete win-win.
Naturally, I thought it would be great if I could check out this app and find out whether it actually delivers – so that you don’t have to!
Stay tuned.
What Is Honeydue?
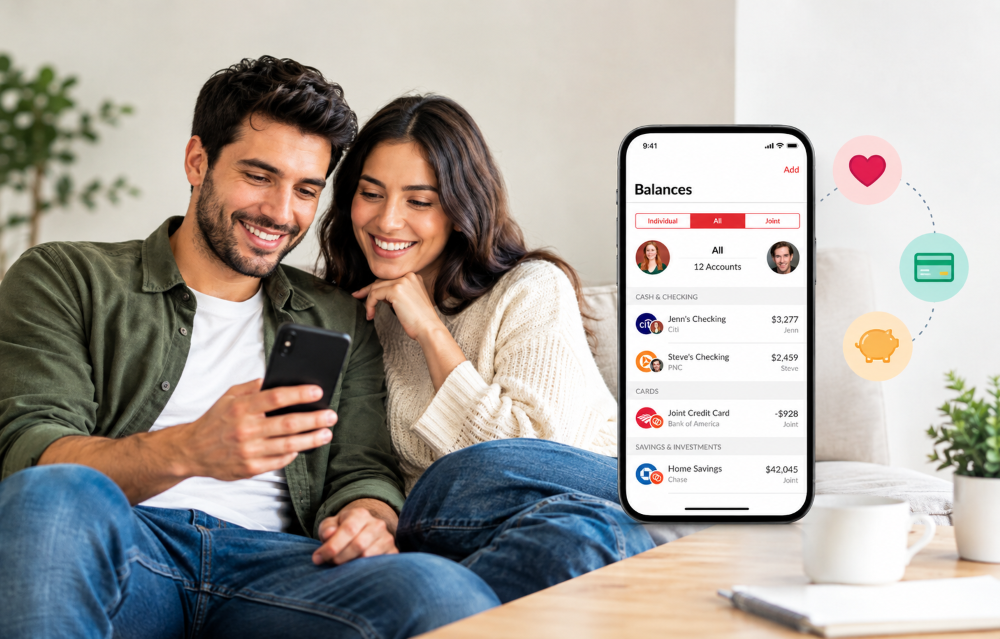
This app brings individual and shared financial information into one mobile app so partners can see their money in one place, monitor spending, coordinate bills, and discuss transactions.
The app supports bank accounts, loans, investments, and credit cards with account connections available across multiple countries and thousands of financial institutions.
In this context, I want to highlight what makes Honeydue stand out – you don’t have to merge your account with that of your partner.
Instead, you can decide how much information you want to share. And so can your partner. For instance, you can share your transaction details, but choose to keep your account private.
That way, you don’t have to give up individual control for the sake of merging finances – financial visibility shouldn’t take away control for you.
How Honeydue Works:
The basic setup is straightforward.
Both partners create accounts and connect the financial accounts they want to monitor. Honeydue then brings balances and transactions into the app.
From there, couples can:
- monitor spending
- create household spending limits
- categorize transactions
- add custom categories
- track bills
- receive bill reminders
- split expenses
- comment on transactions
- communicate through in-app chat
The app automatically categorizes spending, while users can create their own categories when the defaults do not fit their household.
The result is less about creating a perfect personal budget and more about giving two people a shared financial picture.
The Sharing Controls Are The Real Differentiator:
This is probably the most important feature to understand before using Honeydue. Connecting your account does not mean your partner automatically gets to see everything.
I love how the app lets users decide how much information they want to reveal about their accounts.
For instance, you might share:
- Nothing: Your partner does not see the account.
- Balance only: Your partner can see how much is in the account but not individual transactions.
- Balance and transactions: Your partner can see both.
And that distinction can matter in real relationships.
Also, someone might want their partner to know that they have enough money available for a shared expense without wanting every personal purchase to become a conversation.
Why? Because financial transparency does not have to mean financial surveillance. Honeydue’s sharing model recognizes that difference.
Budgeting In Honeydue:
Honeydue includes basic budgeting tools rather than trying to replicate a full financial planning system.
Couples can create spending limits for categories such as household expenses, food, entertainment, or other areas relevant to them.
The app can notify users as they approach those limits.
That works particularly well for couples who need awareness rather than an elaborate budgeting methodology.
For example, you might not need a complicated zero-based budgeting system. You might simply need to know: “Have we already spent too much on eating out this month?”
Honeydue is better suited to that kind of everyday question.
Related Article For You: Budgeting Apps For Couples: 12 Best Apps To Manage Money Together In 2026.
Bill Tracking Is Another Practical Feature:
Shared bills create a surprisingly common source of friction.
Someone forgets the internet bill. Someone assumes the other person paid the electricity bill. A subscription renews without either person noticing.
Honeydue allows couples to add recurring bills and set reminders for upcoming payments.
That does not replace a proper financial plan.
But it can remove some of the administrative work that couples otherwise manage through spreadsheets, messages, calendar reminders, or memory.
Splitting Expenses Without Keeping A Separate Spreadsheet:
Honeydue also lets couples split all expenses and even track who owes what. This can be useful when partners maintain separate accounts but share household costs.
Now, imagine one person pays the grocery bill. Another pays the electricity bill. And a third expense goes on a shared credit card.
Instead of reconstructing everything at the end of the month, the couple can use Honeydue to keep track of individual and shared expenses.
The feature is not revolutionary.
Also, the useful part is having it inside the same system as the rest of the household’s financial information.
Honeydue Turns Transactions Into Conversations:
One of the more unusual features is the ability to communicate around individual transactions.
Partners can leave comments on expenses and use reactions or messages inside the app. That may sound like a novelty.
Also, it is actually connected to a real problem with shared finances.
Money discussions often happen after something has already gone wrong. A transaction appears on a bank statement.
Someone asks what it was. The other person does not remember. And a small expense becomes an unnecessary argument.
So, by attaching communication directly to the transaction, Honeydue gives couples a place to clarify what happened while the information is still visible.
It does not solve financial disagreements. It can make them easier to discuss.
Is Honeydue Free?
Honeydue is currently free to use, with no standard monthly subscription required for its core app. Independent reviews also note that couples can leave some sort of recurring tips, while the app has historically used advertising as part of its business model.
That free model is a major part of its appeal.
Also, many personal finance apps put advanced budgeting, planning, or reporting features behind subscriptions.
Honeydue takes a simpler approach. And the trade-off is that the feature set is also more limited than some paid budgeting platforms.
You May Also Love To Read: Apps For Couples: The Digital Tools That Can Actually Make Life Together Easier.
What Honeydue Does Not Do Particularly Well:
The app’s simplicity is both its strength and its limitation. Honeydue is not designed to be a comprehensive financial planning platform.
Current reviews point to several limitations.
There is no full desktop version, so couples who like managing finances on a laptop may find the mobile-only experience restrictive.
Moreover, the budgeting tools are also relatively basic compared with dedicated paid budgeting applications.
Some users have reported issues around transaction updates, categorization, and the depth of spending analysis.
Also, recent app-store reviews, for example, mention delayed transactions and a lack of more advanced automation or long-term spending views.
These complaints do not mean the app is unusable. They point to a more useful distinction: Honeydue was created to make shared everyday money management easier.
It is not trying to replace a full financial planning system.
Is Honeydue Safe?
Any app that connects financial accounts deserves a closer look at security and privacy.
Honeydue says it uses encryption and multifactor authentication to protect user information. Its current app listings also describe encrypted data in storage and transit.
Independent reviews report that Honeydue uses financial-data connection services to link accounts rather than requiring users to hand over their banking passwords directly to the app.
But security should not be reduced to a single feature or certification.
Before connecting an account, users should still review the app’s current privacy policy, account-sharing controls, supported institutions, and the permissions associated with the connection.
The bigger question is also whether you actually need to connect every account.
Honeydue gives users the option to control what their partner sees, so there is little reason to share more information than the couple actually needs.
Honeydue Is Not The Same As A Joint Bank Account:
This distinction is important.
Honeydue’s budgeting app is primarily a financial-management layer. Moreover, it helps couples view and coordinate existing accounts.
A joint bank account is different. It creates an actual shared financial account where both people have ownership and access.
Honeydue is now also developing a separate Joint Banking offering.
Its website describes the product as a joint account with features including real-time balances, spending notifications, budgeting, ATM access, Apple Pay and Google Pay, and FDIC-insured deposits.
The current site presents the program as a waitlist rather than a generally available product. So couples should not assume that downloading Honeydue means they are opening a joint bank account.
They are two different parts of the product ecosystem.
Honeydue’s Direction Is Changing
There is another reason the app is worth watching.
Honeydue’s current Google Play listing says Mission Lane acquired Honeydue to support couples and families in their credit journeys.
At the same time, Honeydue is positioning its Joint Banking product around a more complete shared-money experience.
That suggests the product is moving beyond simple expense tracking.
Moreover, the interesting question is whether Honeydue can connect its original strength, helping couples discuss money, with a broader banking and credit experience.
For now, the safest way to think about Honeydue is still as a couples-focused money management app, with additional joint-banking functionality being developed.
Who Should Use Honeydue?
Honeydue makes the most sense for couples who:
- want a joint view of household finances
- maintain separate bank accounts
- want access over what their partner sees
- need simple budgeting tools
- regularly split expenses
- want reminders for shared bills
- prefer managing finances from a phone
- want a free solution
Also, it can actually work for couples who are not married. The underlying use case is not “married couples with joint accounts.” Instead, it is two people who need to coordinate money.
Who Might Want Something Else?
Honeydue might not be a good fit if you:
- want detailed financial forecasting
- need sophisticated budgeting automation
- prefer desktop financial software
- want extensive investment analysis
- need advanced reporting
- want highly customizable financial planning
- expect every transaction to update instantly
- want a full financial dashboard rather than a couples-focused budgeting tool
In those cases, a broader personal finance platform may make more sense.
The important thing is not whether Honeydue has fewer features. Instead, it is whether those additional features solve a problem you actually have.
The Bigger Idea Behind Honeydue:
The most interesting thing about Honeydue is not its expense categories or bill reminders. Instead, it is the problem the app chooses to solve.
Most financial software assumes that the individual is the customer.
Honeydue assumes that money management can be a shared activity without making every financial decision completely joint.
That is a subtle difference.
Two people can share rent, groceries, subscriptions, vacations, and financial goals while still maintaining some individual financial independence.
A useful couples finance app needs to accommodate both sides.
- Shared responsibility.
- Individual boundaries.
Honeydue is built around that tension.
Final Verdict: Is Honeydue Worth Your Time?
Honeydue is not trying to be the most sophisticated budgeting platform available.
Instead, its appeal comes from something much simpler.
It gives couples a shared place to see money, discuss spending, coordinate bills, and split expenses, while allowing both people control over how much information they might share.
That makes it particularly useful for couples who are financially connected but do not want to merge every account or transaction.
Also, its limitations are equally clear.
The experience is mobile-focused, budgeting remains relatively simple, and users looking for advanced financial planning may eventually need another tool.
So the real question is not whether Honeydue can manage every aspect of your financial life. It cannot.
The better question is whether you need a simple system for managing your financial life, especially when you are in a relationship.
And for that specific problem, Honeydue’s approach makes a lot more sense.
You Can Also Check:
- NoteIt App Review: Is This Tiny Widget Actually A Cute Way To Stay Connected?
- Cozi App Review: Can It Actually Make Family Life Easier?
- AnyList Review: Is This Grocery List App Worth Using?